Why Your Federal Tax Bracket May Not Tell You What the Next Dollar Costs
Knowing your federal tax bracket is useful, but it does not always tell you what an additional dollar of retirement income will actually cost.
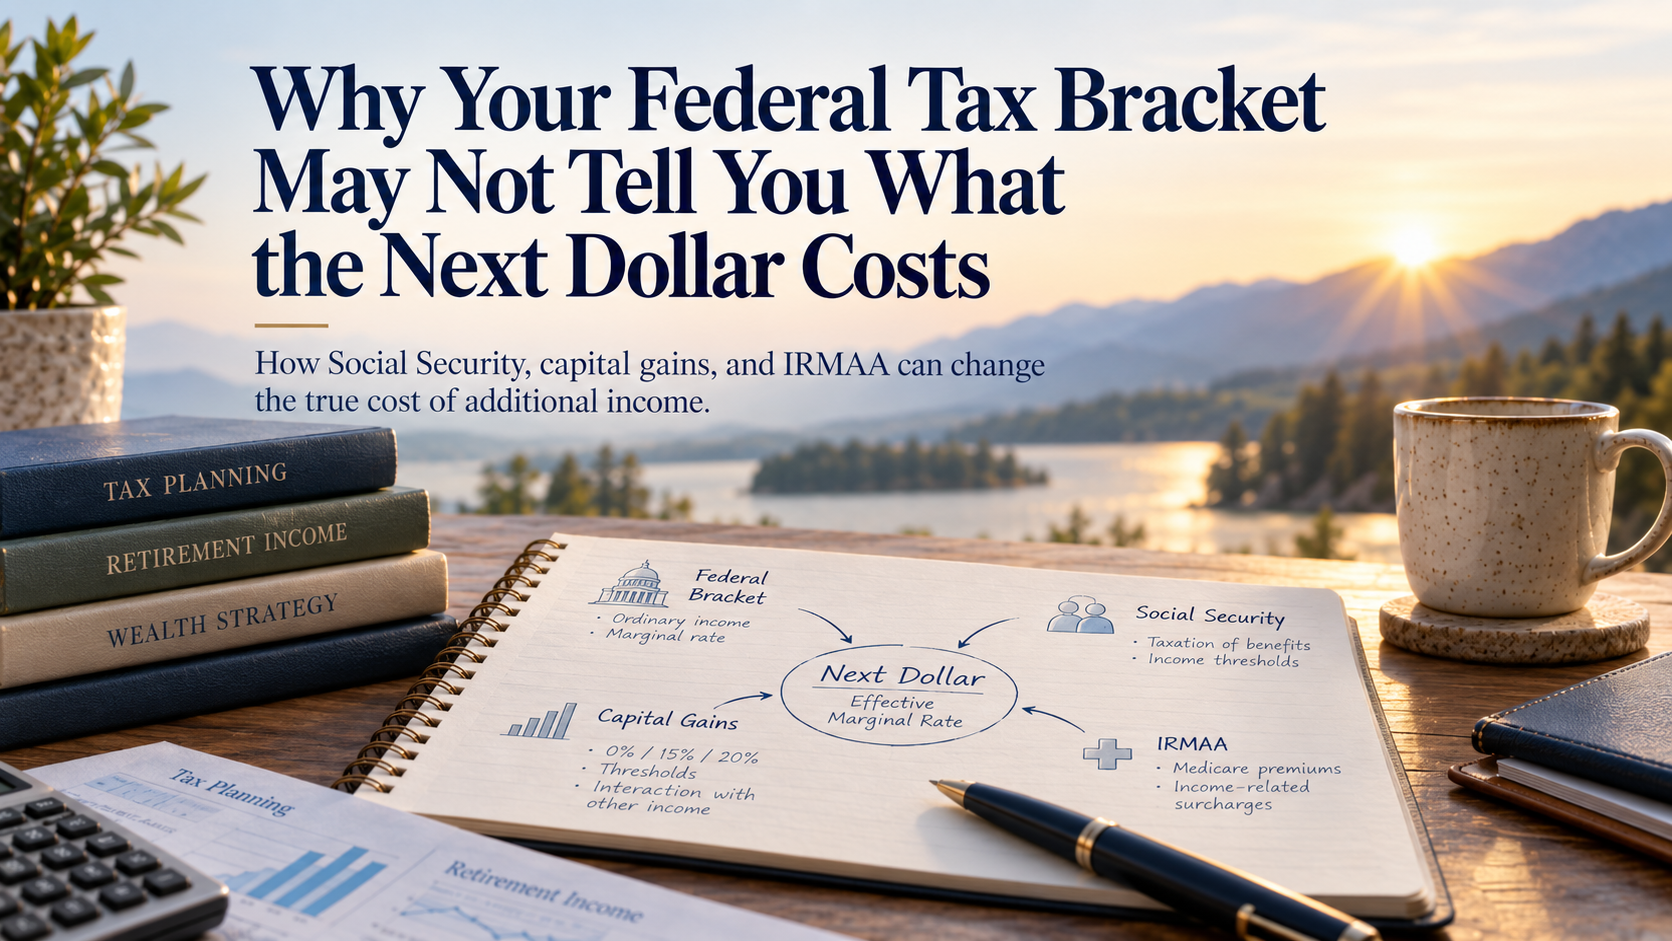
In retirement, additional income can affect more than the tax bracket itself. It may cause more Social Security benefits to become taxable, change the rate applied to capital gains or qualified dividends, or push income across a Medicare premium threshold.
That is why retirement tax decisions often need to be evaluated using the effective marginal tax rate, not simply the federal marginal tax bracket shown on a tax table.
What Is a Federal Marginal Tax Rate?
Your federal marginal tax rate is the statutory tax rate applied to the next dollar of taxable ordinary income while you remain within a particular tax bracket.
For example, someone in a 22% federal bracket may reasonably assume that another dollar of taxable income will create approximately 22 cents of additional federal income tax.
Sometimes that is what happens.
But retirement income can interact with other parts of the tax system, causing the actual incremental cost to be higher—or occasionally lower—than the statutory bracket alone suggests.
What Is an Effective Marginal Tax Rate?
An effective marginal tax rate looks at how much your total tax liability changes when your income changes.
That distinction matters.
A retiree may technically remain within the same federal tax bracket while an IRA withdrawal or Roth conversion causes other income to become taxable at the same time.
In that situation, the statutory bracket has not changed.
But the amount of income exposed to tax has.
The effective marginal tax rate captures that interaction.
This should not be confused with an average or effective tax rate, which generally describes total tax as a percentage of total income for the year.
An average tax rate tells you something about the year as a whole.
A marginal rate is more useful when evaluating the consequence of the next decision.
How Can Social Security Increase Your Effective Marginal Tax Rate?
Social Security provides one of the clearest examples.
Depending on other income, none, some, or as much as 85% of Social Security benefits may be included in taxable income.
This creates a range in which earning or withdrawing another dollar can cause not only that dollar to become taxable, but also cause an additional portion of Social Security benefits to become taxable.
Suppose a retiree is within the range where an additional $1 of income causes another $0.85 of Social Security benefits to become taxable.
The tax calculation is no longer responding to only $1 of additional taxable income.
It may effectively be responding to $1.85.
The retiree can remain in the same statutory federal bracket while experiencing a substantially higher effective marginal rate.
Eventually the interaction ends once the maximum taxable portion of Social Security has been reached. But while a retiree is moving through that range, the federal bracket alone can provide an incomplete picture.
Can Ordinary Income Affect Capital Gains Taxes?
Yes.
Long-term capital gains and qualified dividends receive preferential federal tax rates, but those rates depend in part on overall taxable income.
This creates another potential interaction.
A retiree might have long-term gains that would otherwise fall within the 0% capital-gains range. An additional traditional IRA withdrawal or Roth conversion increases ordinary taxable income.
Even if the additional ordinary income remains in the same ordinary-income tax bracket, it can use taxable-income capacity that had allowed some capital gains to remain in the 0% range.
Part of those gains may then become subject to the next capital-gains rate.
The additional tax associated with the retirement-income decision therefore may include both:
- tax on the additional ordinary income, and
- additional tax on capital gains or qualified dividends already present on the return.
Again, simply looking at the ordinary federal bracket does not reveal the full marginal effect.
How Can Medicare IRMAA Change the Cost of Additional Income?
Medicare adds another layer, although it is important to distinguish an income-related Medicare premium from an income tax.
Medicare Part B and Part D premiums can include an Income-Related Monthly Adjustment Amount, commonly called IRMAA.
IRMAA is based on modified adjusted gross income and generally uses tax information from two years earlier.
Unlike a traditional marginal income-tax bracket, IRMAA operates through income tiers.
Crossing a threshold can increase Medicare premiums for the year even when the amount of income above the threshold is relatively small.
For that reason, a Roth conversion, capital gain, IRA withdrawal, or other income decision close to an IRMAA threshold can create an additional cost that does not appear in the federal tax bracket.
Technically, that cost is not part of the federal income-tax rate.
Economically, however, it may still matter when deciding whether recognizing additional income is worthwhile.
Why Does This Matter for Roth Conversions?
Roth conversions are often discussed in terms of “filling up” a federal tax bracket.
That can be a useful starting point.
It is not always the end of the analysis.
Suppose a retiree has room remaining in a particular federal bracket. A larger conversion might still cause additional Social Security benefits to become taxable, move capital gains into a higher rate, or cross an IRMAA threshold.
Looking only at the statutory bracket could make the conversion appear less expensive than it actually is.
But the opposite mistake is also possible.
The goal should not automatically be to avoid every year in which the effective marginal rate becomes elevated.
Paying a higher rate today may sometimes be reasonable if doing so reduces exposure to larger required distributions, higher future tax rates, survivor filing-status changes, or other constraints later in retirement.
The relevant question is not:
How do we pay the lowest tax this year?
It is:
What are the consequences of recognizing this income now compared with the alternatives available over time?
Why Does This Matter for Retirement Withdrawals?
The same reasoning applies when deciding where spending should come from.
Assume a household needs an additional $50,000.
That spending requirement can potentially be supported in several ways:
A traditional IRA withdrawal.
A Roth distribution.
A sale from a taxable investment account.
Cash already held outside the portfolio.
Each source can produce a different tax result.
And each may affect future years differently.
The question therefore is not simply which account has available money.
The decision needs to consider the tax consequences of producing the income, how those consequences interact with the rest of the return, and what using that resource today means for the resources available later.
Why Isn't the Effective Tax Rate on My Tax Return Enough?
A completed tax return tells us a great deal about what happened during the year.
It can show total income, taxable income, capital gains, deductions, taxes, and many other useful pieces of information.
But the average rate for the year does not necessarily tell us what another $10,000, $50,000, or $100,000 of income would have cost.
That requires a marginal analysis.
A useful retirement tax projection therefore does more than estimate the final tax bill.
It evaluates what changes as additional income is introduced.
Where does Social Security taxation change?
Do capital gains move into another rate?
Does Medicare MAGI approach another threshold?
What happens if income is recognized this year instead of a later year?
Those are forward-looking questions.
How Does This Fit Into Retirement Coordination?
This is where tax planning connects to the broader retirement structure.
The Retirement Coordination Framework™ follows the sequence:
Spending → Income → Tax → Investment
Spending identifies what needs to be supported.
Income determines where those resources may come from.
Tax sequencing evaluates the consequences of using those income sources and when they should be used.
Investment alignment then considers how the remaining assets should be positioned based on the responsibilities they continue to carry.
Tax is therefore not an isolated calculation.
It is a constraint that helps shape retirement-income decisions.
The Lowest Current Tax Rate Is Not Always the Goal
Retirement tax planning is not simply a search for the lowest possible tax bill each year.
Sometimes recognizing additional income today creates a higher current-year cost but improves the choices available later.
Other times, delaying income can be valuable.
The answer depends on what the household is trying to support, which resources are available, and what consequences the decision creates across multiple years.
That is why a federal tax bracket is useful information—but not always the number that matters most.
The more important question is what actually changes when the next retirement-income decision is made.